Why does a 20-metre stroll in Harare give an explanation for the way forward for African fintech? When Juan Seco left Wall Boulevard inner most fairness for African tech, he realised the most important hole wasn’t advanced economic tool—it was once what occurs after a remittance arrives. From auditing American Categorical in New York to development JumiaPay and scaling Mukuru’s neobank infrastructure throughout Southern Africa, Seco joins PATHISANI MOYO in our newest version of Espresso With…
A couple of days sooner than talking with Juan Seco, Leader Expansion Officer and Managing Director for East Africa at Mukuru, a virtual economic amenities corporate, I discovered myself reflecting on a dialog with my 76-year-old mom.
She lives in Harare; I reside in Johannesburg. Having transferred budget to her by the use of Mukuru, I known as to test if the cash had arrived safely. Her reaction was once characteristically direct: “Mntanami (my son), don’t ever ship me cash thru your mates once more.”
The budget had landed immediately on her cell phone, permitting her to gather the money in individual after a temporary 20-metre stroll. That modest 20-metre walk captures the core philosophy in the back of Mukuru’s enlargement a ways higher than any company presentation.
The 20-metre lesson
For the Spanish-born govt, who spent years advising tier-one economic establishments in New York sooner than relocating to Nairobi, the way forward for African fintech isn’t about crafting hyper-complex economic tools. It’s about getting rid of the friction that hinders how other folks obtain, retailer, transfer, and spend their cash.
That concept underpins Seco’s definition of South Africa-headquartered Mukuru as a “remittance-led neobank.”
It is helping give an explanation for why an organization best possible recognized for helping migrants send money home is fast paced into on a regular basis virtual economic amenities, from wallets and playing cards to bills and banking infrastructure.
These days, Mukuru operates throughout greater than 60 nations, serving 17.6 million consumers thru an unlimited bodily and virtual payout community throughout Southern and East Africa.
Seco’s trail to African economic infrastructure was once anything else however linear. Born in Madrid, he spent his early life between France and Luxembourg sooner than finding out finance and world industry at McGill College in Canada.
He started his profession at PwC in Spain, auditing economic establishments similar to American Categorical and Prudential, sooner than moving to New York to paintings in private-equity mergers and acquisitions. On paper, it was once a textbook company profession; in observe, it was once an hard regimen.
The turning level arrived when Seco and his spouse—a Colombian company attorney who grew up in Kenya—welcomed a daughter, adopted temporarily through twins. Managing 3 kids underneath 3 along two high-powered company careers proved unsustainable.
“We discovered ourselves operating loopy hours with 3 children underneath 3,” Seco recollects. His spouse posed a decisive query: “You’ve been unsatisfied for years doing paintings you aren’t hooked in to. Why now not make a metamorphosis?”
The solution was once Nairobi, the Kenya capital town, the place Seco took what he describes as an enormous pay reduce to enroll in Jumia, Africa’s e-commerce trailblazer. It was once a dramatic transfer from the arena of New York finance into one in all Africa’s maximum formidable generation corporations on the time.
He would spend kind of a decade within the Jumia ecosystem, operating throughout generation, trade, and fiscal amenities. It was once there that Seco started to look African economic infrastructure in a different way.
The issue that modified how he noticed African fintech
As Jumia’s leader economic officer (CFO), he encountered an issue that regarded mundane however had huge implications. The corporate operated throughout more than one African markets, and consumers continuously paid in money. Money-on-delivery was once dear and operationally painful. Virtual bills, against this, may just make the industry extra environment friendly.
However development the ones fee connections was once now not easy. The similar generation workforce running throughout a lot of nations and industry strains was once time and again development integrations with other mobile-money methods, together with M-Pesa, Kenya’s pioneering cellular cash provider.
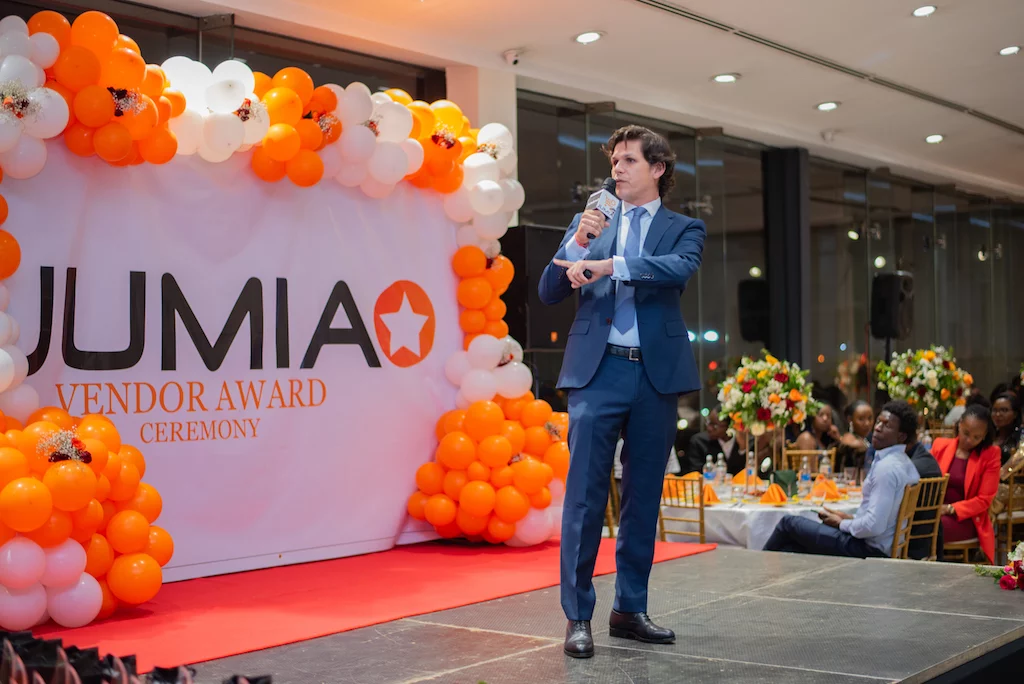
Seco realised Jumia’s drawback was once larger than including extra fee integrations. It wanted a layer within the heart to glue them. “That is damaged. We’d like one thing within the heart,” was once necessarily the realization he reached.
That thinking helped lead to Jumia Pay, the e-commerce corporate’s fintech bills platform, and, later, a deeper focal point on economic generation.
He noticed equivalent issues at the banking aspect. Company economic amenities that are meant to were virtual nonetheless concerned bulky processes. A company card may just successfully behave like a pay as you go device. Transactions may just require bodily interplay with financial institution branches.
For any person who had spent years uncovered to virtual banking in North The us, the distinction was once putting. The chance was once to not replica the banking methods he had recognized somewhere else however to construct across the realities of African shoppers.
At Jumia Pay, that pondering expanded into lending, together with working-capital merchandise for dealers, buy-now-pay-later integrations, shopper credit score in Egypt, microloans in Nigeria, and different economic merchandise designed round transactions already going down at the platform.
From remittances to a “remittance-led neobank”
That lesson adopted him to Mukuru, where Seco joined in 2023 and located one thing many fintechs spend years looking to construct: believe.
Mukuru had spent twenty years transferring cash throughout borders, incomes the believe of hundreds of thousands of shoppers who depended on it to ship cash house. However Seco noticed that the individual receiving the cash was once simply as vital as the individual sending it.
Seco spotted that folks in nations similar to Zimbabwe, Malawi, and Botswana weren’t essentially asking for a classy new economic product. They sought after the object they already understood to paintings higher.
That was the root of his thought for a remittance-led neobank, with Mukuru the usage of the believe it has constructed thru transferring cash throughout borders as the place to begin for a broader economic dating with its consumers.
“Remittance is the end of the spear,” Seco mentioned. “It’s the first transaction and, in lots of circumstances, the primary time we have now that dating with the buyer. The chance is to take that believe and make the buyer’s on a regular basis economic existence more straightforward.”
In line with Seco, remittance is the access level that provides consumers a explanation why to believe the platform and creates the chance for Mukuru to serve extra in their on a regular basis economic wishes.
As an alternative of the cash arriving and straight away disappearing into money, it could actually stay in a pockets. The buyer pays a invoice, make a purchase order, obtain a wage, ship cash somewhere else, or sooner or later get entry to different economic amenities.
Seco is cautious to not body Mukuru’s enlargement as merely promoting extra merchandise to current consumers. As an alternative, he desires every new provider to suit naturally into how consumers already organize their cash and clear up a economic want they have already got. “They will have to be an extension or adjoining to what the buyer already does,” he mentioned.
Making the cash usable after it arrives
That pondering is changing into an increasing number of visual in Mukuru’s merchandise.
In Botswana, as an example, Mukuru recently launched a physical Visa debit card connected to its pockets, permitting consumers to spend from their pockets steadiness at shops and withdraw money from computerized teller machines (ATMs). The theory is deceptively easy: cash despatched through a relative in another country can develop into straight away usable cash fairly than one thing that calls for some other step sooner than it may be spent.
Seco sees this as the sensible expression of Mukuru’s philosophy of assembly consumers the place they’re. “At Mukuru, we all the time speak about assembly our consumers the place they’re,” he mentioned.

That implies assembly consumers anyplace they’re, whether or not thru Mukuru’s agent community, USSD, WhatsApp or an increasing number of thru virtual accounts. That is the place the Financial institution 0 partnership in South Africa turns into vital.
Mukuru has partnered with Bank Zero to supply banking infrastructure in the back of its new account and card providing. Shoppers can obtain salaries and different bills, make digital bills and use their playing cards for on a regular basis transactions, whilst Mukuru continues to possess the buyer dating and enjoy.
This is a fashion that is smart for Seco as a result of Mukuru does now not must develop into a standard financial institution so as to be offering extra banking capability.
Financial institution 0 supplies the underlying banking infrastructure, whilst Mukuru brings the shoppers, distribution, generation and financial-services enjoy.
The partnership is already important in scale. About 500,000 Mukuru consumers are being migrated onto Financial institution 0’s infrastructure, contributing to a mixed Financial institution 0 buyer base of greater than 700,000 finish consumers.
The 20-metre philosophy
Seco believes the importance of the ones numbers lies much less of their scale than in what they permit: consumers can transfer from money to virtual economic amenities with no need to start out their economic adventure all over the place once more, crucial shift in markets the place money and virtual cash nonetheless coexist.
“Simply because any person transacts in money will have to now not imply they’ve get entry to to fewer economic amenities,” Seco defined to TechCabal.
For Seco, good fortune isn’t measured in app downloads or virtual card issuances by myself, however in making the transition between money and virtual price utterly frictionless.
“Simply because any person transacts in money does now not imply they will have to be excluded from formal economic amenities,” Seco emphasizes. Whether or not interacting by the use of USSD, WhatsApp bots, agent networks, or debit playing cards, Mukuru’s mandate is to fulfill shoppers inside of their current conduct.
Which brings the narrative again to a 76-year-old mom in Harare.
For fintech analysts, economic inclusion is continuously mentioned in summary metrics: regulatory licences, transaction throughput, and API integrations. For a mom accumulating her per 30 days toughen, it boils right down to one thing way more sensible: the cash arrives safely, predictably, and with out useless trip.
Her adventure was once 20 metres. In an business continuously obsessive about technological novelty, Juan Seco’s imaginative and prescient for Mukuru proves that probably the most profound economic inventions shorten the space between receiving cash and the usage of it.
True scale calls for transferring past surface-level integrations to tough execution. We’ve filtered the noise out of Moonshot 2026, optimising the convention strictly for high-calibre connections between startup founders, world economic operators, endeavor leaders and folks rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.