Airtel Cellular Trade N.V., the Netherlands-based fintech arm of Airtel Africa, plans to release a digital fee card in Kenya, putting in a brand new contest with Safaricom over world on-line spending.
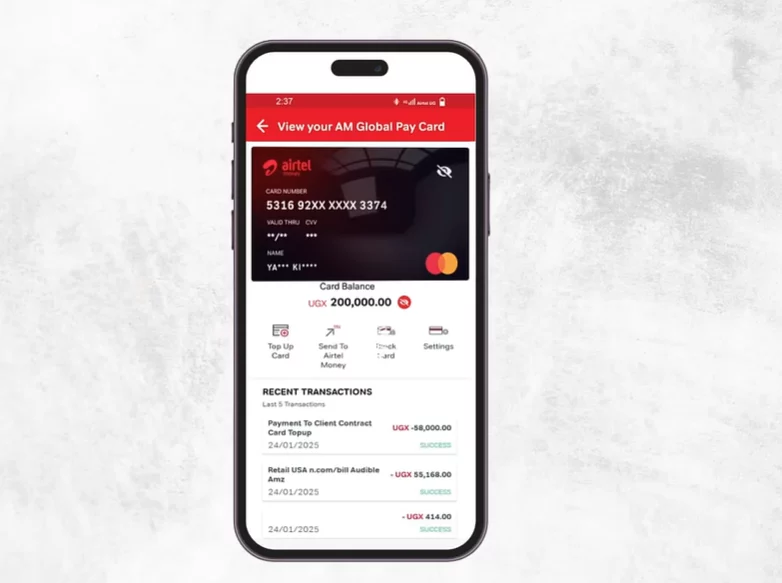
Evolved with Mastercard, the Digital Card Quantity (VCN) will combine with Airtel Cash wallets, enabling shoppers to pay for products and services on international platforms comparable to Amazon and Netflix with no conventional checking account.
The release places Airtel Money World Pay in direct pageant with M-PESA GlobalPay, Safaricom’s digital Visa card introduced in 2022. Airtel is coming into a marketplace the place Safaricom has a longtime lead, however the contest is ready greater than the fee networks in the back of the playing cards. It additionally issues how shoppers fund transactions, organize on-line spending, and get right of entry to credit score when their pockets balances run low.
The M-PESA GlobalPay card can draw on Fuliza, an overdraft facility that shall we eligible shoppers whole on-line bills when their M-PESA steadiness is inadequate. Airtel Cash’s pay as you go card lacks this option, requiring shoppers to fund it sooner than making a purchase order.
Information from the Communications Authority of Kenya displays M-PESA’s cell cash marketplace proportion has slipped to 88.8% in June 2026, down from just about 95% in 2023. Airtel Cash’s proportion rose to 11.1% over the similar length. The figures point out a gentle shift within the aggressive steadiness, even though Safaricom’s lead stays considerable.
World trade gives a brand new earnings movement
Kenya’s rising use of virtual products and services offers each operators a reason why to compete for world bills. Streaming subscriptions, device products and services, and in a foreign country e-commerce platforms permit cell cash suppliers to succeed in spending that would possibly another way glide thru credit cards.
Netflix, which entered Africa in 2016, is one instance of ways world virtual products and services have change into a part of on a regular basis spending. Digital playing cards let shoppers with out financial institution accounts pay those traders by means of cell cash, extending wallets’ succeed in past home transfers and service provider bills.
For operators dealing with force on home fee fees, cross-border transactions additionally be offering a technique to earn earnings from world trade. Foreign currencies conversion and service provider bills can generate source of revenue past the core trade of transferring cash between native accounts.
Safaricom’s international bills operation, which incorporates cross-border transfers, digital playing cards, and app retailer billing, generated KES 4.76 billion ($37.2 million) within the financial year ended March 2026, up 22.3% from the former 12 months. M-PESA generated KES 182.7 billion (323.1 billion) in transaction worth throughout 46.4 billion transactions.
The figures display why even a reasonably small slice of M-PESA’s trade is essential. World bills can give a contribution to earnings expansion with out requiring Safaricom to win a related proportion of Kenya’s home cell cash marketplace. The chance for Airtel is to seize a portion of that spending as extra shoppers use its pockets for on-line purchases.
Throughout 14 African markets, Airtel’s cell cash operation generated $1.3 billion in revenue, up from $747 million. The corporate has issued more than 875,000 virtual cards in Uganda, Zambia and Tanzania since 2025 and plans to introduce the carrier in Kenya, the Democratic Republic of Congo and Gabon.
Credit score and safety separate the playing cards
The 2 merchandise take other approaches to investment on-line bills. M-PESA GlobalPay hyperlinks to the client’s M-PESA pockets. Against this, Airtel’s VCN type calls for shoppers to switch price range from their primary Airtel Cash pockets to the digital card sooner than making a purchase order.
The setup shall we Airtel shoppers ring-fence cash for on-line purchases, maintaining the remainder of their pockets steadiness cut loose card transactions. It additionally offers them higher keep an eye on over subscription bills and their on-line spending.
Shoppers nonetheless want to give protection to their account credentials and observe transactions. The level of coverage additionally depends upon the controls to be had to freeze or organize the cardboard, to dispute unauthorised bills, and to stop additional fees.
Safaricom’s authentic digital Visa card design used a card verification worth (CVV) that buyers generated during the M-PESA app after coming into their PIN. Each and every code lasted half-hour and may well be used handiest as soon as, restricting the window wherein it may well be used if uncovered.
Safaricom introduced the overdraft choice for GlobalPay in 2026, permitting eligible shoppers to finish on-line bills when their pockets steadiness is inadequate. The characteristic can assist save you subscription bills from failing, nevertheless it additionally way automatic fees would possibly draw on credit score, leaving shoppers with an overdraft to pay off.
Airtel’s pay as you go type does now not be offering an similar overdraft facility, so shoppers should have enough price range at the digital card to finish a purchase order. This can be much less handy, nevertheless it additionally prevents the cardboard from extending spending thru an similar credit score line.
A challenger nonetheless faces a scale drawback
Safaricom’s huge buyer base offers GlobalPay a longtime target market, whilst familiarity with M-PESA could make shoppers much less prone to modify fee strategies.
Airtel’s card may just attraction to shoppers who already use Airtel Cash and need an immediate path to world traders. Its regional rollout additionally offers the corporate revel in to attract on because it enters the Kenyan marketplace.
Shoppers will wish to evaluate foreign currency echange fees, transaction limits, acceptance charges, dispute dealing with and the benefit of managing card main points. Airtel’s pricing will probably be in particular essential as a result of a lower-cost card may just draw in price-sensitive customers, whilst unclear charges may just blunt the attraction of its pay as you go design.
Airtel has but to expose all of the main points Kenyan shoppers will wish to assess the carrier, together with its foreign currency echange fees. Safaricom’s GlobalPay applies a foreign currency echange markup, making the overall charge of a purchase order a related level of comparability.
The release won’t erase Safaricom’s lead in cell cash. Nonetheless, it is going to give Airtel otherwise to compete for buyer spending, this time on the on-line checkout moderately than thru home transfers.
True scale calls for transferring past surface-level integrations to powerful execution. We’ve filtered the noise out of Moonshot 2026, optimising the convention strictly for high-calibre connections between startup founders, international monetary operators, endeavor leaders and folks rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.