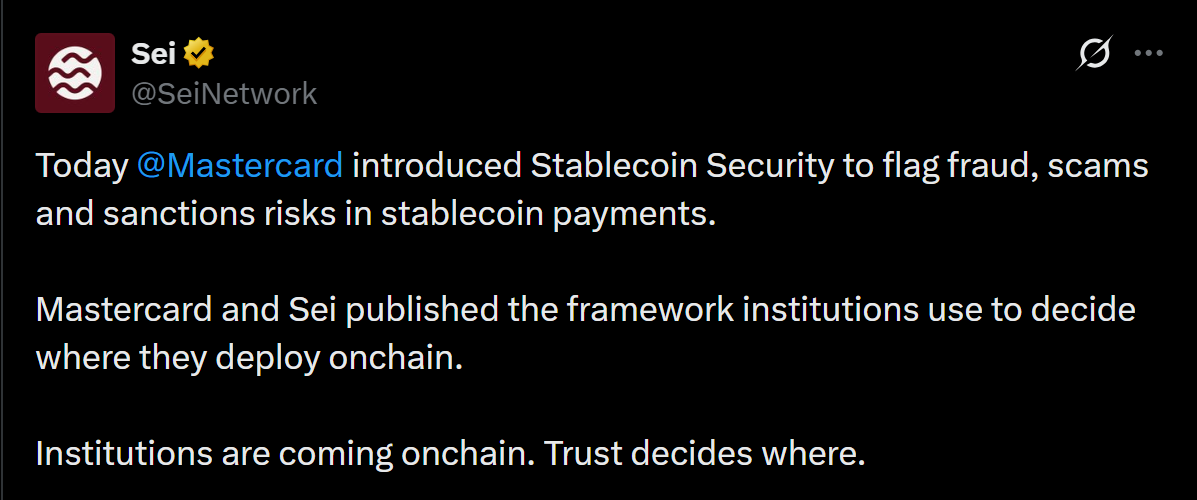
Mastercard introduced stablecoin safety to offer banking and finance companies. The safety characteristic comes with equipment to discover fraudulent actions, scams, and possible violations of sanctions rules related to stablecoin transactions.
In doing so, this gives monetary establishments with the chance to judge conceivable dangers previous to suspicious transactions being processed.
With extra complicated varieties of stablecoin bills turning into more and more not unusual, early detection of possible issues is turning into extra vital.
Those cost chains can complicate chance review and make post-settlement tracking much less efficient.
Without borders.xyz and Keyrails are some of the first contributors to fortify the brand new product’s North American release, and Mastercard expects to supply it globally starting in 2027.
Coinbase and Thunes extend stablecoin payout succeed in
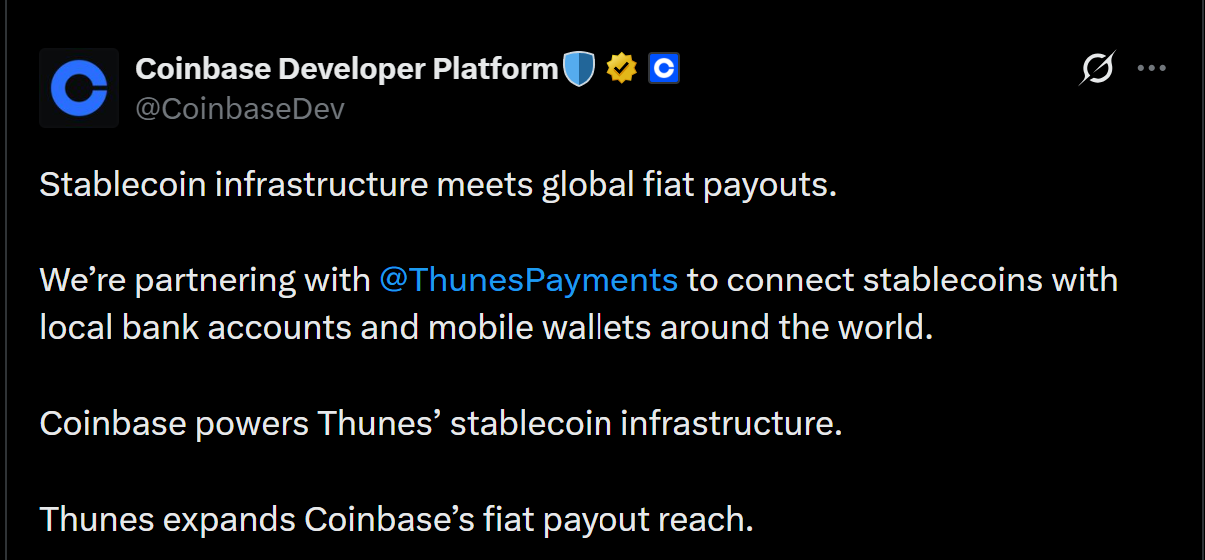
Following the rush to make stablecoin bills more secure, Coinbase and Thunes are running in combination to resolve every other primary factor in enabling the standard adoption of stablecoin bills. That is finished by means of offering recipients with rapid get entry to to stablecoin bills at their native checking account or cellular pockets.
Via their joint effort, Coinbase’s stablecoin-enabled cost techniques will attach without delay to Thunes’ Direct World Community. This offers direct connections to over 140 nations and 90 other currencies by way of financial institution accounts and cellular wallets.
In the end, whether or not Coinbase and Thunes’ movements will lead to vital adoption relies on a number of elements. This comprises the provision of payout choices, the efficiency of the payout procedure itself, and precise utilization ranges amongst traders, shoppers, and recipients.
May just higher infrastructure power stablecoin adoption?
Higher infrastructure is vital to changing larger stablecoin adoption into upper quantity cost job. Mastercard is bettering transaction screening, whilst Coinbase and Thunes are increasing get entry to to native payouts.
In combination, those tasks cope with two primary limitations combating wider adoption of stablecoin safety and accessibility. Establishments can assess dangers previous and succeed in recipients via native banks and cellular wallets.
As such, those enhancements may make cross-border transactions more uncomplicated for each customers and trade homeowners.
On the other hand, more potent infrastructure does now not ensure sustained call for. Allium’s 2026 data displays cost volumes emerging whilst stablecoin provide stays in large part flat.
Significantly, the knowledge means that current quantities of stablecoins are expanding in frequency as they proceed to flow into. So, if repeated usage will increase together with settled price, then stablecoins may enjoy broader enchantment out of doors of the crypto ecosystem.
Conversely, if precise utilization fails to extend in spite of advanced infrastructure building, then infrastructure expansion would possibly outpace precise utilization.
Ultimate Abstract
- Mastercard’s Stablecoin Safety may spice up consider by means of screening fraud and sanctions dangers ahead of agreement.
- Coinbase and Thunes extend stablecoin payouts, however adoption will depend on actual transaction call for.